Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.Yes, mortgage rates have been ticking up lately –

Dated: September 11 2023
Views: 132
If you’re hoping to buy a home this year, you’re probably paying close attention to mortgage rates. Since mortgage rates impact what you can afford when you take out a home loan – and affordability is a challenge today – it’s a good time to look at the big picture of where mortgage rates have been historically compared to where they are now. Beyond that, it’s important to understand their relationship with inflation for insights into where mortgage rates might go in the near future.
Freddie Mac has been tracking the 30-year fixed mortgage rate since April of 1971. Every week, they release the results of their Primary Mortgage Market Survey, which averages mortgage application data from lenders across the country (see graph below):
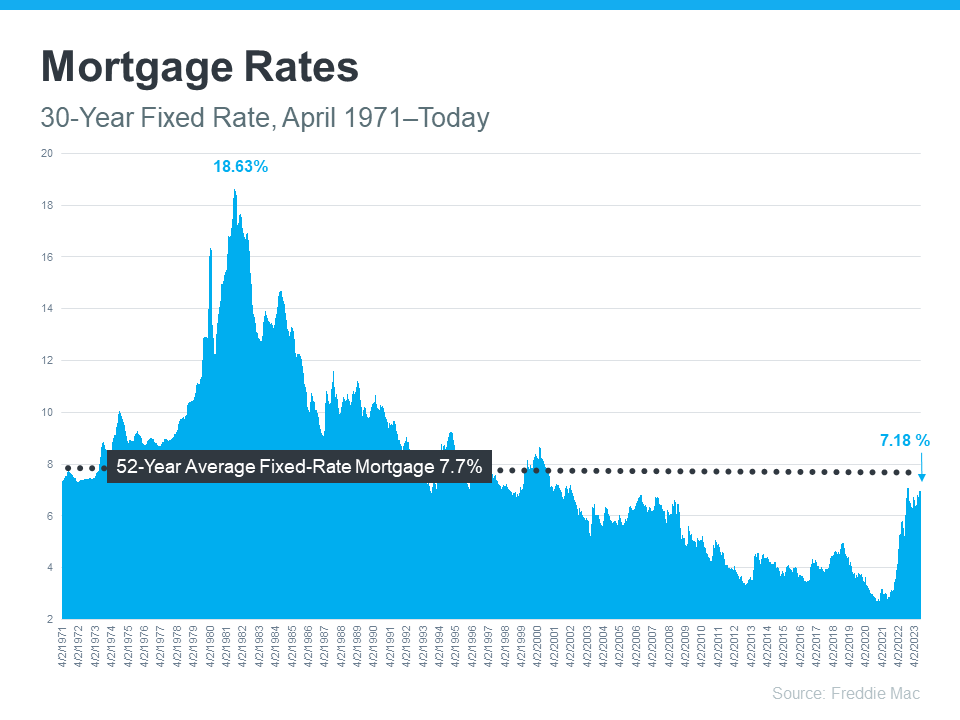
Looking at the right side of the graph, mortgage rates have increased significantly since the start of last year. But even with that rise, today’s rates are still below the 52-year average. While that historical perspective is good context, buyers have gotten used to mortgage rates between 3% and 5%, which is where they’ve been over the past 15 years.
That’s important because it explains why the recent jump in rates might have you feeling sticker shock even though they’re close to their long-term average. While many buyers have adjusted to the elevated rates over the past year, a slightly lower rate would be a welcome sight. To determine if that’s a realistic possibility, it’s important to look at inflation.
The Federal Reserve has been working hard to lower inflation since early 2022. That’s significant because, historically, there’s been a connection between inflation and mortgage rates (see graph below):
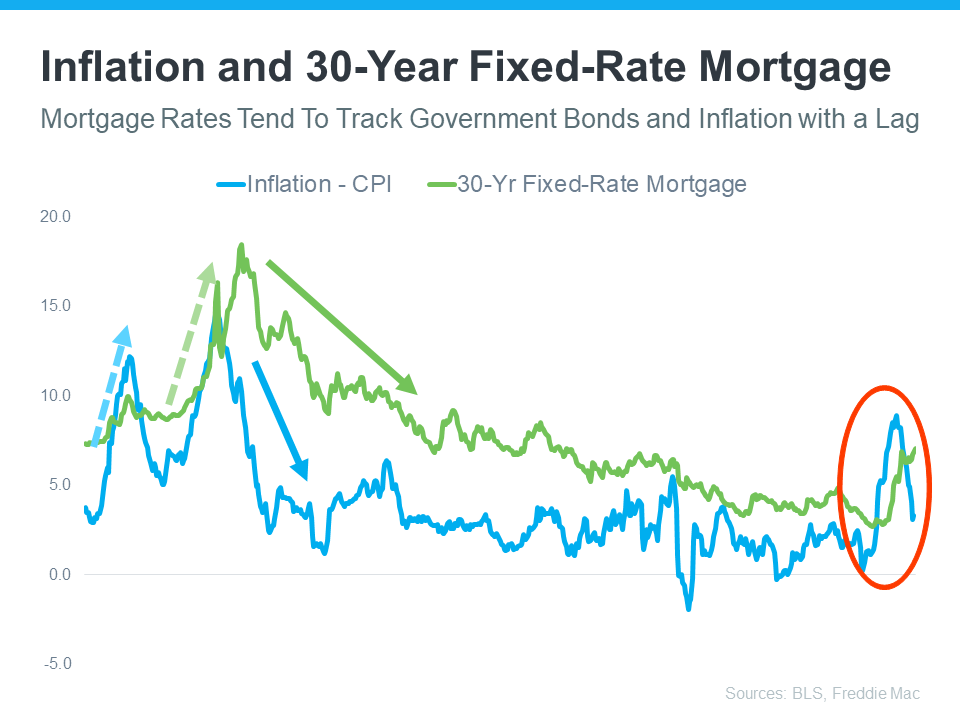
This graph shows a pretty reliable relationship between inflation and mortgage rates. Looking at the left side of the graph, each time inflation moves significantly (shown in blue), mortgage rates follow suit shortly after (shown in green).
The circled portion of the graph points out the most recent spike in inflation, with mortgage rates following closely behind. As inflation has moderated a bit this year, mortgage rates haven’t yet made a similar move.
That means, if history is any guide, the market is waiting for mortgage rates to follow inflation and head back down. It’s impossible to accurately predict where mortgage rates will go for sure, but moderating inflation means mortgage rates going down in the near future would fit a well-established trend.
To understand where mortgage rates may be going, it’s helpful to look at where they’ve been in the past. There’s a clear connection between inflation and mortgage rates, and if that historical relationship holds true, the recent decline in inflation may mean good news for the future of mortgage rates and your homeownership goals.
As the Team Director of Torres Team Realty, I have spent many hours educating myself and our team on multiple avenues of Real Estate. All agents are members of the California Association of Realtors a....
Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.Yes, mortgage rates have been ticking up lately –
Ask a couple people how the housing market is doing and you’ll probably get a couple different answers. That’s because right now, the market runs on 2 very different tracks, split by
You’ve been waiting for something to change before you buy. It just might not be the thing you expected…While everyone’s paying attention to mortgage rates, only the savviest
Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you’ve caught the buzz and wondered whether that money
 Based on information from California Regional Multiple Listing Service, Inc. as of September 22, 2026 7:07 AM UTC This information is for your personal, non-commercial use and may not be used for any purpose other than to identify prospective properties you may be interested in purchasing. Display of MLS data is usually deemed reliable but is NOT guaranteed accurate by the MLS. Buyers are responsible for verifying the accuracy of all information and should investigate the data themselves or retain appropriate professionals. Information from sources other than the Listing Agent may have been included in the MLS data. Unless otherwise specified in writing, Broker/Agent has not and will not verify any information obtained from other sources. The Broker/Agent providing the information contained herein may or may not have been the Listing and/or Selling Agent.
Based on information from September 22, 2026 7:07 AM UTC The information being provided by CRMLS is for the visitor's personal, noncommercial use and may not be used for any purpose other than to identify prospective properties visitor may be interested in purchasing. The data contained herein is copyrighted by CRMLS, CLAW, i-Tech MLS, PSRMLS and/or VCRDS and is protected by all applicable copyright laws. Any dissemination of this information is in violation of copyright laws and is strictly prohibited.
Any property information referenced on this website comes from the Internet Data Exchange (IDX) program of CRMLS. All data, including all measurements and calculations of area, is obtained from various sources and has not been, and will not be, verified by broker or MLS. All information should be independently reviewed and verified for accuracy. Properties may or may not be listed by the office/agent presenting the information.
 This information is deemed reliable but not guaranteed. You should rely on this information only to decide whether or not to further investigate a particular property. BEFORE MAKING ANY OTHER DECISION, YOU SHOULD PERSONALLY INVESTIGATE THE FACTS (e.g.square footage and lot size) with the assistance of an appropriate professional. You may use this information only to identify properties you may be interested in investigating further. All uses except for personal, non-commercial use in accordance with
the foregoing purpose are prohibited. Redistribution or copying of this information, any photographs or video tours is strictly prohibited. This information is derived from the Internet Data Exchange (IDX) service provided by San Diego MLS. Displayed property listings may be held by a brokerage firm other than the broker and/or agent responsible for this display. The information and any photographs and video tours and the compilation from which they are derived is protected by copyright.Compilation © 2026 San Diego MLS. Last Updated: September 22, 2026 6:54 AM UTC
Show More...
 Last updated: September 22, 2026 6:52 AM UTC Property Information © 2026 MLSListings Inc. All rights reserved. Listing information is deemed reliable but not guaranteed. The data relating to real estate for sale on this display comes in part from the Internet Data Exchange program of the MLSListingsTM MLS system. Real estate listings held by brokerage firms other than eXp Realty of Southern California, Inc. CA DRE#02187306 are marked with the Internet
Data Exchange and detailed information about them includes the names of the listing brokers and listing agents.
The information being provided by CARETS (CLAW, CRISNet MLS, DAMLS, CRMLS, i-Tech MLS, and/or VCRDS)
is for the visitor's personal, non-commercial use and may not be used for any purpose other than to identify
prospective properties visitor may be interested in purchasing.
Any information relating to a property referenced on this web site comes from the Internet Data Exchange (IDX)
program of CARETS. This web site may reference real estate listing(s) held by a brokerage firm other than the
broker and/or agent who owns this web site.
The accuracy of all information, regardless of source, including but not limited to square footages and lot sizes, is
deemed reliable but not guaranteed and should be personally verified through personal inspection by and/or with
the appropriate professionals. The data contained herein is copyrighted by CARETS, CLAW, CRISNet MLS,
DAMLS, CRMLS, i-Tech MLS and/or VCRDS and is protected by all applicable copyright laws. Any dissemination
of this information is in violation of copyright laws and is strictly prohibited.
CARETS, California Real Estate Technology Services, is a consolidated MLS property listing data feed comprised
of CLAW (Combined LA/Westside MLS), CRISNet MLS (Southland Regional AOR), DAMLS (Desert Area MLS),
CRMLS (California Regional MLS), i-Tech MLS (Glendale AOR/Pasadena Foothills AOR) and VCRDS (Ventura
County Regional Data Share)
Show More...
 The information being provided by Conejo Simi Moorpark Association of REALTORS ® ("CSMAR") is for the visitor's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties visitor may be interested in purchasing. Any information relating to a property referenced on this web site comes from the Internet Data Exchange ("IDX") program of CSMAR. This web site may reference real estate listing(s) held by a brokerage firm other than the broker and/or
agent who owns this web site. Any information relating to a property, regardless of source, including but not limited to square footages and lot sizes, is deemed reliable but not guaranteed and should be personally verified through personal inspection by and/or with the appropriate professionals. The data contained herein is copyrighted by CSMAR and is protected by all applicable copyright laws. Any dissemination of this information is in violation of copyright laws and is strictly prohibited. 2026
Show More...
 The MLS™ I-Tech ® All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in
purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than eXp Realty of Southern California, Inc. CA DRE#02187306 may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 22, 2026 7:04 AM UTC
Show More...
 The information being provided by Lake Havasu Association MLS is for the consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumer may be interested in purchasing. Any information relating to real estate for sale referenced on this web site comes from the Internet Data Exchange (IDX) program of the Lake Havasu Association MLS. eXp Realty of Southern California, Inc. CA DRE#02187306 is not a Multiple Listing Service (MLS), nor
does it offer MLS access. This website is a service of eXp Realty of Southern California, Inc. CA DRE#02187306, a broker participant of Lake Havasu Association MLS. This web site may reference real estate listing(s) held by a brokerage firm other than the broker and/or agent who owns this web site.
The accuracy of all information, regardless of source, including but not limited to open house information, square footages and lot sizes, is deemed reliable but not guaranteed and should be personally verified through personal inspection by and/or with the appropriate professionals. The data contained herein is copyrighted by Lake Havasu Association MLS and is protected by all applicable copyright laws. Any unauthorized dissemination of this information is in violation of copyright laws and is strictly prohibited.
Copyright 2026 Lake Havasu Association MLS. All rights reserved. IDX information is provided exclusively for consumers' personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. All information is deemed reliable, but not guaranteed. This data is provided by the Lake Havasu Association MLS.
Data last updated: September 22, 2026 6:35 AM UTC
Show More...
